From DowJo — where this research becomes practice. Train your judgment before you risk your money.
Course Research · Episode 6
AI Eats Electricity — and Then the Grid Fights Back
The evidence-led takeaway
"Electricity" is not one constraint. It is six — component supply, generation, transmission, interconnection, permitting, and the local politics of a place.
 Ask Jo about this research
Jo reads this note before answering. Sign in to ask Jo with this evidence attached — you come straight back here.
In brief
What this research concludes
"Electricity" is not one constraint. It is six — component supply, generation, transmission, interconnection, permitting, and the local politics of a place. They bind at different times, in different places, with different economics, and almost every version of this story collapses them into one word. The binding item is not the electrons and it is not the equipment. It is the powered building: the shell, the interconnection, the permit, and the crew that installs it.
The judgment skill this hands over
Before acting on a shortage, say out loud which of four claims you are making and name the evidence each one requires. Important needs a share. Tight needs a price or a wait. Sold out needs a seller. Binding needs a buyer saying they could not proceed. Then say WHICH constraint you mean — most shortage stories are rung two, dressed as rung four, about a word that is doing the work of six.
What we investigated
The question, and who it looks at
This is episode 6 of Investing in the AI Era, a 14-episode course. The film tells the story; this note is the research behind it, kept inspectable.
Who and what this looks at
How we tested it
Researched to be refuted, not confirmed
Candidate claims went to an independent pass instructed to refute them against primary sources. Survivors became evidence; casualties became the refused list below.
The method, in the research team's own words
Adversarial multi-lens campaign: 453 candidate claims across 14 lenses, every claim sent to an independent fact-checker instructed to REFUTE it, verdicts recorded as SUPPORTED / CORRECTED / MISLEADING / UNSUPPORTED. The full harvest (3.0 MB) was collapsed exactly once into course/research/AI06-shortlist.json with the refuters' corrected text substituted for the original claim text; this packet is the further distillation to the facts the film actually narrates. Two findings that appeared to refute the episode's thesis (GE Vernova's 'not the gating item' and the IEA's high-end-memory binding constraint) were verified against primary sources and SHARPENED the thesis rather than defeating it — see course/AI06-HANDOFF.md section 2. Where a shortlist verdict is CORRECTED or MISLEADING, the corrected text is what appears here and what is narrated. Research budget for this compilation: 4 lookups authorised, 0 spent — all four open items were answered by joining material already inside the packet.
What the evidence says
53 claims survived refutation
Each carries its source, the date the thing happened and the date it was said — two different facts — and its limits, stated by the research team rather than left for you to discover.
- FactJournalismF01
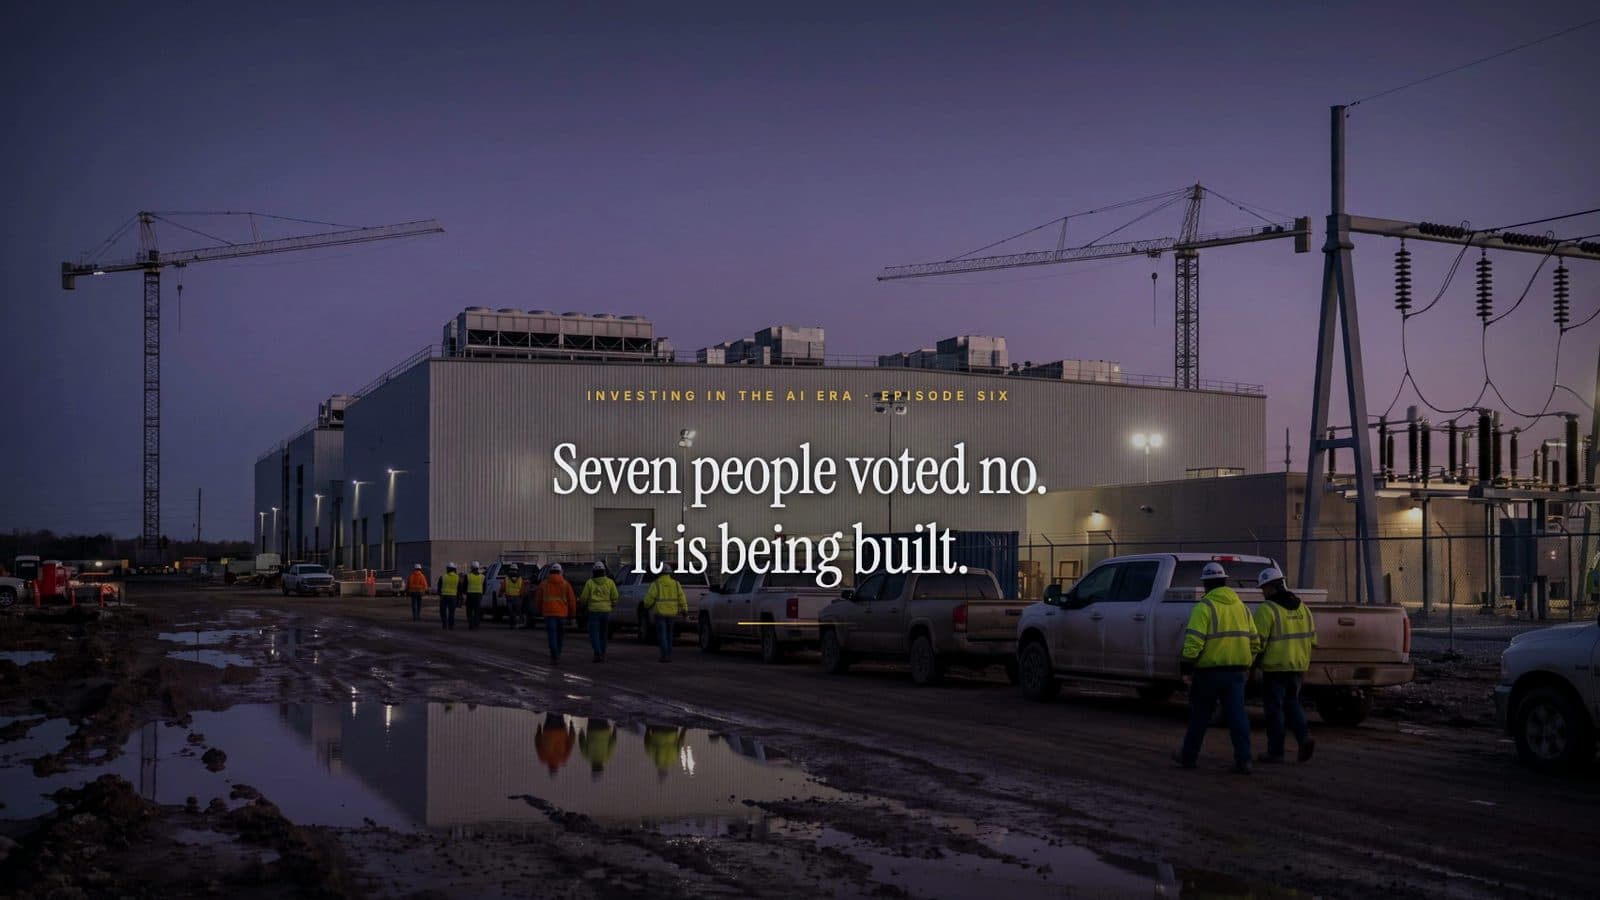
On 6 August 2025 Tucson's Mayor and Council voted 7-0 to end negotiations over Project Blue, a 290-acre data-centre campus developed by Beale Infrastructure, citing water supply and ratepayer concerns.
Source: AZ Luminaria and Tucson Spotlight / KVOA contemporaneous reporting of the 6 August 2025 Mayor and Council vote
Event 6 Aug 2025 · Published 8 Jan 2026
Limits: Secondary reporting; corroborated across three Tucson outlets and the dcmap.us policy tracker. Amazon's involvement was reported, never confirmed by the company.
Research note
Shortlist H387 (CORRECTED) and H388. The corrected mechanism in F02 is load-bearing and must be narrated with it.
- FactJournalismF02
The vote did not stop the project, because the land was never inside the city. The 290-acre site sits in unincorporated Pima County, so what the Council actually terminated was ANNEXATION and the negotiations attached to it — a refusal to bring the land in, not a refusal to let it be built.
Source: AZ Luminaria, 'Two Southern Arizona data centers move forward — so do fights over power, water and growth'
Event 6 Aug 2025 · Published 8 Jan 2026
Limits: Municipal boundaries, not policy, determined the outcome. This is the correction that makes the cold open honest: Tucson never held the veto it appeared to exercise.
Research note
Shortlist H387. The earlier draft of this claim said the project 'moved to Marana' — that is FALSE and belongs to a different, larger Beale project. See X03.
- FactJournalismF03
Project Blue proceeded: Pima County supervisors approved a development agreement with Beale on 16 December 2025, the land sale closed on 24 December 2025, and construction had begun by April 2026.
Source: AZ Luminaria construction reporting, corroborated by Pima County board records
Event 16 Dec 2025 · Published 24 Apr 2026
Research note
Shortlist H387.
- FactJournalismF04
The Arizona Corporation Commission approved the Tucson Electric Power supply agreement for the site on 3 December 2025 by 4 votes to 1. The dissent was Commissioner Rachel Walden.
Source: Arizona Corporation Commission decision, reported by KJZZ and corroborated by KVOA
Event 3 Dec 2025 · Published 9 Dec 2025
Research note
Shortlist H387/H388. The named dissent is what gives the cold open a person without spending a research lookup.
- FactJournalismF05
The project switched from water-intensive cooling to air cooling, which routes around the water objection and raises the electricity draw instead.
Source: KJZZ 'The Show', corroborated by KVOA and Tucson Spotlight
Event Dec 2025 · Published 9 Dec 2025
Limits: The reported withdrawal of AWS as operator was never confirmed by Amazon and is NOT narrated.
Research note
Shortlist H388. This is 'bottlenecks move' made concrete: a community can win a water fight and get the data centre anyway, drawing more power instead.
- FactFrontier · Aug 2026Primary sourceF06
US total electricity end use ran essentially flat for thirteen years and then broke upward: 3,890,231 GWh in 2007 against 3,856,377 GWh in 2020 — a 0.9% DECLINE over thirteen years — then 4,195,085 GWh in 2025.
Event 20 2000 · Published Aug 2026
Limits: 2025 is preliminary and subject to revision. 'End use' = retail sales to ultimate customers plus direct use. The 2020 dip is COVID-affected.
Research note
Chartable series, 26 annual datapoints. The episode's strongest single visual.
- FactFrontier · Aug 2026Primary sourceF07
EIA notes that starting in 2023, part of the change in industrial and commercial retail sales reflects IMPROVED REPORTING of data-centre and cryptocurrency-mining operations — a reporting change, not purely a demand change.
Source: US EIA, Monthly Energy Review, Table 7.6 notes (opens eia.gov)
Published Aug 2026
Research note
Narrated ON the break, not omitted. The film states the claim at full strength and then immediately says what part of the line is measurement rather than demand.
- FactPrimary sourceF08
At the end of 2025, roughly 2,061 GW of generation and storage capacity across 8,244 projects was actively seeking transmission interconnection in the United States — 1,312 GW of generation and 749 GW of storage.
Event 31 Dec 2025 · Published Jun 2026
Limits: LBNL states plainly: 'Not all of this capacity will be built.'
Research note
Shortlist H034.
Show the remaining 45 pieces of evidence
- FactPrimary sourceF09
That 2,061 GW is GENERATOR interconnection to the transmission grid. It is explicitly not load interconnection, not distribution-connected, and not behind-the-meter. It is not the data-centre queue and must never be narrated as one.
Source: Lawrence Berkeley National Laboratory, Queued Up: 2026 Edition (opens emp.lbl.gov)
Event 31 Dec 2025 · Published Jun 2026
Research note
Shortlist H034 limitations, verbatim in substance. Conflating the two is the single most common error in AI-power commentary, and the film disarms its own biggest number.
- FactPrimary sourceF10
Active natural gas capacity in US interconnection queues rose 86% during 2025 to 253 GW, while solar (773 GW, -19%), storage (749 GW, -16%) and wind (220 GW, -19%) all declined. Only about 10 GW of nuclear was active.
Source: Lawrence Berkeley National Laboratory, Queued Up: 2026 Edition, slides 13, 16 (opens emp.lbl.gov)
Event 31 Dec 2025 · Published Jun 2026
Limits: Queue presence is cheap and non-binding; the gas surge may partly reflect speculative positioning ahead of expected demand.
Research note
Shortlist H014. Attention points at nuclear; developer behaviour points at gas, solar and storage.
- FactPrimary sourceF11
The IEA's own physical-bottleneck section lists bottlenecks in the plural, with transformers at 2-3 years, gas turbines at around 5 years, and grid connections at 5-10 years. Electricity is never singled out as THE binding one.
Published 16 Apr 2026
Research note
Verified against the primary PDF in the AI06 handoff, section 2.
- FactResearchF12
Wood Mackenzie's Q2 2025 benchmark put US power transformer lead times at 128.0 weeks and generator step-up transformers at 143.4 weeks — and both had DECLINED quarter over quarter, power transformers by 10.4 weeks.
Event 30 Jun 2025 · Published 30 Sep 2025
Limits: This is a Q2 2025 reading, NOT a 2026 reading. Multiple 2026 articles quote '128 weeks' as if current — that is a dating error and the film must not repeat it. The underlying benchmark is subscription-only, so the 2026 series could not be verified.
Research note
Shortlist H446. Narrate the date and the direction, never the level as current. See X07.
- FactPrimary sourceF13
Large power transformers were a long-lead item long before the AI cycle: a 2014 Department of Energy study already described them as requiring substantial capital and a lead time in excess of six months.
Source: US Department of Energy, Large Power Transformers and the US Electric Grid (2014)
Published Apr 2014
Research note
Shortlist H203. The base rate: this constraint predates the story being told about it.
- FactPrimary sourceF14
On GE Vernova's first-quarter 2026 earnings call, 22 April 2026, chief executive Scott Strazik said: 'in many of the cases with these projects, the gas turbines are really not the gating item. When you're talking about a three-year cycle from when a project starts, the EPC buildout, the permitting, the fuel availability.'
Source: GE Vernova Q1 2026 earnings call, company-published webcast transcript (opens gevernova.com)
Event 22 Apr 2026 · Published 22 Apr 2026
Limits: The chief executive has an interest in not being blamed for delays — which is the point: this is the party with the least incentive to say it.
Research note
Verified verbatim in the company's own transcript PDF (AI06 handoff, section 2). Shortlist H117/H118.
- FactPrimary sourceF15
He said it twice on the same call, the second time unprompted: 'generally speaking, don't find our heavy-duty gas turbines to be the gating item on a directionally three-year cycle time right now.'
Source: GE Vernova Q1 2026 earnings call, company-published webcast transcript (opens gevernova.com)
Event 22 Apr 2026 · Published 22 Apr 2026
Research note
Verified verbatim, handoff section 2.
- FactPrimary sourceF16
On the same call he put GE Vernova's own turbine lead time at 'directionally at about three years'. The turbines are not the gate because everything else takes exactly as long.
Source: GE Vernova Q1 2026 earnings call, company-published webcast transcript (opens gevernova.com)
Event 22 Apr 2026 · Published 22 Apr 2026
Limits: This is the load-bearing nuance. Turbines are CO-BINDING, not abundant. Narrating this as 'turbines are easy to get' inverts it.
Research note
Shortlist H032. Handoff section 2 marks this as the sentence the critic missed.
- FactFrontier · Jul 2026Primary sourceF17
GE Vernova's gas equipment backlog and slot reservations reached 116 GW during the second quarter of 2026, up from 100 GW in a single quarter — but only 53 GW of that is firm backlog. The company expects to end 2026 with at least 125 GW under contract, 'making us mostly sold out through 30'.
Source: GE Vernova Q2 2026 earnings call and Q1 2026 call transcripts (opens gevernova.com)
Event 30 Jun 2026 · Published 22 Jul 2026
Limits: 'Sold out' means heavy-duty units at GE Vernova specifically. Slot reservations are not firm orders — 63 of the 116 GW are reservations.
Research note
Shortlist H127/H128/H032. AI05 already spent the 20 GW-signed/3-shipped figure; this is a different disclosure.
- InterpretationPrimary sourceF18
Scope discipline on the quote: he said 'many', not 'most', and 'these projects' means his gas-power projects generally. Data centres are only around a fifth of that book.
Source: GE Vernova Q1 2026 earnings call, company-published webcast transcript (opens gevernova.com)
Event 22 Apr 2026 · Published 22 Apr 2026
Research note
Handoff section 2. Stated on screen so the quote is not over-read.
- FactResearchF19
On the BG2 podcast published 31 October 2025, Microsoft chief executive Satya Nadella said: 'the biggest issue we are now having is not a compute glut, but it's a power. And it's sort of the ability to get the builds done fast enough, close to power. So if you can't do that, you may actually have a bunch of chips sitting in inventory that I can't plug in. And in fact, that is my problem today. It's not a supply issue of chips. It's actually the fact that I don't have warm shells to plug into.'
Source: BG2Pod with Brad Gerstner and Bill Gurley, 'All things AI' — primary audio, transcribed at approximately 20:00-21:00
Event 31 Oct 2025 · Published 31 Oct 2025
Limits: A podcast remark, not a filing or a prepared earnings statement. He gave no quantity, no site and no timeline. Dated late 2025 — do not present as a current-quarter fact.
Research note
Shortlist H154/H216/H217. This is the buyer, which is what rung four requires.
- InterpretationResearchF20
Read the noun. What Nadella says is missing is not electrons — it is WARM SHELLS: finished buildings, with power and cooling, ready to plug into. That is construction, siting and energisation as much as generation.
Source: BG2Pod, as above; analysis of the quoted words
Event 31 Oct 2025 · Published 31 Oct 2025
Research note
Shortlist H216/H217 teaching_use. This is the sentence that turns the episode's thesis from 'electricity' into 'the powered building'.
- FactFrontier · Aug 2026Primary sourceF21
NVIDIA's Form 10-Q for the quarter ended 26 July 2026 states: 'Securing land, power, and shell for data centers is a critical phase in the AI infrastructure buildout,' and discloses $56 billion of additional commitments — $36 billion of AI cloud agreements and $20 billion of third-party data-centre leases not yet commenced.
Event 26 Jul 2026 · Published 26 Aug 2026
Limits: These are future commitments by fiscal year, not spending incurred: $26 billion of the $56 billion sits in fiscal 2032 and beyond, and only $6 billion in fiscal 2028.
Research note
Shortlist H242.
- FactFrontier · Aug 2026Primary sourceF22
The same filing carries $3,529 million of notional guarantees on select AI cloud partners' land, power and shell data-centre lease obligations, with partners posting $712 million in escrow. NVIDIA discloses that the fair values of these credit derivatives 'were not significant', and the notional was essentially FLAT over six months.
Source: NVIDIA Corporation Form 10-Q, fiscal Q2 2027, derivatives note (opens sec.gov)
Event 26 Jul 2026 · Published 26 Aug 2026
Limits: This is a credit guarantee against partner DEFAULT. It evidences that lessors demanded a stronger counterparty, which mixes power scarcity with partners' own credit. NVIDIA is not a disinterested party. A constraint that is tightening usually shows a RISING number; this one did not move.
Research note
Shortlist H240. The strongest FOR exhibit because it is money rather than words — and the flat notional is narrated with it.
- FactFrontier · Aug 2026Primary sourceF23
In that same document NVIDIA also says: 'We will be shipping both Blackwell and Rubin systems in the future and are currently experiencing certain supply constraints.' It does not say which stage is constrained, does not quantify it, and does not rank it against power.
Source: NVIDIA Corporation Form 10-Q, fiscal Q2 2027 (accession 0001045810-26-000075) (opens sec.gov)
Event 26 Jul 2026 · Published 26 Aug 2026
Limits: The filing contains no reference to HBM, substrates, or constrained wafer or packaging capacity. Calling this 'the chip bottleneck' is an inference the document does not support.
Research note
Shortlist H243. Both constraints, one document, one date.
- FactPrimary sourceF24
The IEA finds that 'in the second half of 2025 and beginning of 2026, global production capacity for high-end memory also emerged as a binding constraint on the rate of AI server production.'
Event 20 2025 · Published 16 Apr 2026
Limits: IEA cites SemiAnalysis, Micron and IDC for the underlying memory figures — near-primary industry sources, not IEA measurements.
Research note
Shortlist H167. Verified verbatim, handoff section 2.
- FactPrimary sourceF25
And the sentence that decides its meaning: high-bandwidth memory production supports a maximum of around 25 GW of AI-ready servers per year through to 2027, 'broadly in line with the rate of capacity additions in the IEA's Base Case'. Memory and power pace each other.
Published 16 Apr 2026
Research note
Verified verbatim, handoff section 2. Memory binds how many servers get built; power binds where they get switched on.
- InterpretationFrontier · Sep 2026Primary sourceF26
The honest verdict on the top rung: there is testimony from a buyer, and there is filed corroboration that land, power and shell is a category worth guaranteeing with money. There is no filed disclosure attributing a specific delayed AI deployment to power.
Source: Synthesis of the AI06 evidence base; the standing AI05 finding, narrowed
Published 2 Sep 2026
Limits: This is the update to Episode 5's standing finding, which recorded a total absence. The absence has narrowed, not vanished, and the film says exactly how far it narrowed.
Research note
Drives ClaimLadder reach = 3.5. See X01: the bar is on the word PROVEN, not on the evidence.
- FactPrimary sourceF27
About 549 GW of US capacity holds a draft or executed interconnection agreement without ever having reached commercial operations — 256 GW of solar, 161 GW of storage, 76 GW of wind and 45 GW of gas.
Event 31 Dec 2025 · Published Jun 2026
Limits: An executed interconnection agreement still does not guarantee construction: financing, offtake and equipment supply remain. No timeline is attached to this 549 GW.
Research note
Shortlist H001. The post-gauntlet cohort — the projects that WON — and it is still sitting there.
- FactPrimary sourceF28
Even in that most-advanced cohort the buildable supply is overwhelmingly solar and storage. Gas is 8% of it and nuclear is absent.
Source: Lawrence Berkeley National Laboratory, Queued Up: 2026 Edition (opens emp.lbl.gov)
Event 31 Dec 2025 · Published Jun 2026
Research note
Shortlist H001, derived from the same four figures and asserted in src/data/ai06-evidence.ts.
- FactFrontier · Aug 2026Primary sourceF29
Oncor, the largest Texas transmission utility, reported an interconnection request queue of 298 GW against an actual peak demand of 31 GW, with 44 GW under ERCOT evaluation in 'Batch Zero'.
Source: Oncor Electric Delivery Company LLC / Sempra, Exhibit 99.2 to Form 8-K (opens sec.gov)
Event 30 Jun 2026 · Published 6 Aug 2026
Limits: 298 GW is a REQUEST queue containing duplicate applications from developers shopping multiple sites. It is not demand. The document never says 'data center'.
Research note
Chartable series. Ten times the utility's own peak demand asked to connect. That ratio is the attrition fact.
- FactFrontier · Aug 2026JournalismF30
A US data-centre policy tracker covering March 2025 to August 2026 records 56 formal public actions across 25 states: 21 moratoriums, 17 state legislative or regulatory actions, 7 enacted ordinances, 6 outright project rejections and 5 executive pauses. 34 were local and 22 statewide.
Source: dcmap.us, US Data Center Policy Tracker (opens dcmap.us)
Event Mar 2025 · Published Aug 2026
Limits: A private aggregator with undisclosed inclusion methodology, not an official registry; it self-declares that smaller local pauses go unreported, so 56 is a floor. Categories overlap and must not be summed; the local/statewide split and the total are the only internally consistent decomposition.
Research note
Shortlist H004. Six outright rejections in twenty months is meaningful friction, not a wall.
- InterpretationJournalismF31
The chart counts ACTIONS, not megawatts. A ban in a rural county with no projects weighs exactly the same as a statewide interconnection freeze. Weighted by affected capacity it would collapse to roughly four jurisdictions.
Source: dcmap.us tracker methodology, assessed (opens dcmap.us)
Published Aug 2026
Research note
Narrated on the frame. The correction is more interesting than the count.
- FactFrontier · Jul 2026Primary sourceF32
PJM's Base Residual Auction cleared at $28.92 per megawatt-day for delivery year 2024/2025, then $269.92 for 2025/2026, $329.17 for 2026/2027, $333.44 for 2027/2028 and $325.00 for 2028/2029.
Source: PJM Interconnection Base Residual Auction Reports, Table 2, and PJM news releases (opens pjm.com)
Event 20 2017 · Published Jul 2026
Limits: Rest of RTO, UCAP resource clearing price. The 2024/2025 and 2025/2026 auctions spanned a change in capacity accreditation rules, so the step between them is not a pure supply-demand comparison.
Research note
Chartable series, 12 delivery years from 2017/2018.
- FactFrontier · Jul 2026Primary sourceF33
The last three prints cleared AT an administrative price cap, not at a market-discovered price. The fall to $325.00 for 2028/2029 is a LOWER COMPUTED CAP, not easing scarcity. The series flattens by construction.
Source: PJM 2027/2028 Base Residual Auction Report and subsequent auction release
Published Jul 2026
Research note
Drawn as an explicit cap line across the last three points. A price that stops rising because it hit a ceiling is not the same fact as a price that stops rising because supply arrived.
- FactPrimary sourceF34
New Jersey's Board of Public Utilities announced residential bill increases of 17.2% to 20.2% effective 1 June 2025. Its president, Christine Guhl-Sadovy, said: 'PJM's recent capacity auction results are the main driver of these increases.'
Event 12 Feb 2025 · Published 12 Feb 2025
Limits: A state regulator's attribution, made when the political stakes were high. It attributes the increase to the CAPACITY AUCTION, not to data centres.
Research note
Shortlist H251. This is where the propagation chain terminates somewhere a viewer lives.
- FactFrontier · Jun 2026Primary sourceF35
And the discipline on that number: by June 2026, EIA shows New Jersey residential prices up only 0.3% year on year. It was a one-time step, not a compounding trend.
Source: US EIA electricity data, New Jersey residential price, assessed against the 2025 step
Event Jun 2026 · Published Jun 2026
Research note
Shortlist H251 limitations. Narrated immediately after F34 so the bill story cannot be over-read.
- FactResearchF36
And it runs the other way too. A Columbia University literature review finds load-growth effects on retail prices are mixed and context-dependent, citing an estimate that for PG&E every 1 GW of new data-centre load could REDUCE average household bills by 1 to 2 percent, by spreading fixed costs over more sales.
Event 23 Jun 2026 · Published 23 Jun 2026
Limits: A literature review, not primary measurement. The PG&E result is jurisdiction-specific and the authors condition it on regulators ring-fencing interconnection costs — which is exactly what has not happened in most PJM states. Local marginal price impacts up to 20% are also reported.
Research note
Shortlist H047.
- FactFrontier · Jul 2026Primary sourceF37
AEP has filed large-load tariff proposals in eight jurisdictions to make data centres pay their own way. Virginia approved Appalachian Power's in the second quarter of 2026: it applies to new loads of 150 MW aggregated or 100 MW individual, with contract terms up to 20 years and take-or-pay provisions written to protect existing customers.
Source: American Electric Power Q2 2026 Form 10-Q, MD&A — large load tariff proposals
Event 30 Jun 2026 · Published 30 Jul 2026
Limits: Tariff designs vary by state and several remain contested; the terms are AEP's characterisation of its own filings.
Research note
Shortlist H009. This is 'the grid fights back' in regulatory form — and it also CAPS the utility.
- FactPrimary sourceF38
New York Executive Order 62, signed 14 July 2026, holds DISCRETIONARY STATE environmental permits issued by the Department of Environmental Conservation for facilities of 50 MW or more. It does not touch local zoning, by-right development or federal permits, and it exempts applications the DEC had already deemed complete.
Source: Office of Governor Kathy Hochul, Executive Order No. 62 (official text) (opens governor.ny.gov)
Event 14 Jul 2026 · Published 14 Jul 2026
Research note
Shortlist H084. 'New York banned data centers' is on the do-not-narrate list — see X04.
- FactPrimary sourceF39
The order sets no expiration date. It lifts when the Department of Public Service submits its report on the final Generic Environmental Impact Statement, and no deadline is written for that study. The widely repeated 'one-year pause' is an outside characterisation, not a term of the order.
Source: Office of Governor Kathy Hochul, Executive Order No. 62 (official text)
Event 14 Jul 2026 · Published 14 Jul 2026
Limits: The only twelve-month deadline in EO 62 attaches to a separate DEC water-withdrawal report, not to the GEIS.
Research note
Shortlist H084. The mechanism is narrower than the headline AND open-ended in a way the headline misses. Both corrections, same order.
- FactFrontier · Aug 2026ResearchF40
On 3 August 2026 Texas Governor Greg Abbott directed the Public Utility Commission and ERCOT to verify and audit every data centre advancing through ERCOT's interconnection process before any additional ones may move forward. ERCOT withheld its scheduled large-load classifications as a result.
Source: Letter from Governor Greg Abbott to the PUCT and ERCOT, 3 August 2026; ERCOT Market Notice M-A080326-01
Event 3 Aug 2026 · Published 3 Aug 2026
Limits: The Governor's letter itself could not be retrieved directly (the state site returned 403); the date and mechanism are corroborated by four law-firm alerts, the trade press and an independent EIA reference. It pauses an interconnection STUDY PROCESS — it is not a construction ban.
Research note
Shortlist H275. 'Texas banned data center construction' is on the do-not-narrate list — see X05.
- FactFrontier · Aug 2026Primary sourceF41
The EIA cut its forecast for Texas electricity load growth in 2027 from 14% to 6% after that announcement, writing that it had lowered the forecast because of the pause.
Source: US EIA, August 2026 Short-Term Energy Outlook (opens eia.gov)
Event 3 Aug 2026 · Published 12 Aug 2026
Limits: A one-month-old policy response; the pause is an audit pending, not a cancellation, and EIA may revise back up. A state-level figure, not national.
Research note
Shortlist H077. A study process — not a ban — moved a federal agency's forecast by eight percentage points.
- FactFrontier · Jul 2026Primary sourceF42
AEP's authorised returns on equity sit in a 9.7% to 9.8% band across jurisdictions — West Virginia 9.75%, Kentucky 9.8%, Ohio 9.7% and 9.84%. Its FERC transmission vehicle REQUESTED a base return of 10.8%.
Source: American Electric Power Form 10-Q, Rate Matters
Event 30 Jun 2026 · Published 30 Jul 2026
Limits: The 10.8% is a REQUEST, not an award; FERC deferred the base ROE to settlement. Authorised return on equity is not earned return on equity.
Research note
Shortlist H010. The one place the mechanism lets a utility earn more is FERC-jurisdictional transmission.
- FactFrontier · Aug 2026Primary sourceF43
CoreWeave's Form 10-Q names specialised construction labour — electricians, mechanical engineers, HVAC technicians, commissioning specialists — as a shortage that could delay completion of new data-centre projects: 'Any inability to secure sufficient skilled labor on acceptable terms could delay the completion of new data center projects.'
Source: CoreWeave, Inc. Form 10-Q for the quarter ended June 30, 2026, Part II Item 1A Risk Factors
Event 30 Jun 2026 · Published 12 Aug 2026
Limits: A risk factor, not a realised delay. Risk factors are shaped by counsel and litigation exposure, not by operational ranking.
Research note
Shortlist H062. The affirmative answer the critics said the research did not contain.
- FactFrontier · Aug 2026Primary sourceF44
The same filing gives power its own dedicated risk-factor heading, stating that limitations on generation, transmission and distribution 'may limit our ability to obtain sufficient power capacity for our potential expansion sites'. It names both, side by side.
Source: CoreWeave, Inc. Form 10-Q, Part II Item 1A Risk Factors
Event 30 Jun 2026 · Published 12 Aug 2026
Research note
Shortlist H062 (CORRECTED). The corrected text is narrated: it is not labour INSTEAD of power, it is both.
- FactFrontier · Jul 2026Primary sourceF45
Comfort Systems USA's revenue from Technology customers rose 105% to $1.917 billion and went from 43.0% to 58.7% of total revenue in a single year. Net income rose 91% to $441.6 million.
Source: Comfort Systems USA Form 10-Q for the quarter ended June 30, 2026 (Revenue by Type of Customer)
Event 30 Jun 2026 · Published 23 Jul 2026
Limits: The company defines 'Technology' as data centres AND chip manufacturing and does not disclose the split. Part of the growth came from six acquisitions; same-store revenue growth was 43.8%. The frequently repeated '+73% backlog' figure is NOT sourced in the Q2 2026 filings and is not narrated.
Research note
Shortlist H048.
- FactFrontier · Jul 2026Primary sourceF46
EMCOR's remaining performance obligations rose 43.9% to a record $17.14 billion, earned at a 10.6% operating margin.
Source: EMCOR Group Q2 2026 earnings release (accession 0000105634-26-000112)
Event 30 Jun 2026 · Published 30 Jul 2026
Research note
Shortlist H083. Breadth of backlog confirms the demand is real; the margin shows who does not capture the rent.
- FactFrontier · Jul 2026Primary sourceF47
Quanta Services grew revenue 41% to $9.56 billion and booked a record $53.4 billion backlog at a 7.3% consolidated operating margin — but that margin ROSE from 5.5% a year earlier, and operating income grew 88% against 41% revenue growth.
Source: Quanta Services Q2 2026 earnings release (Exhibit 99.1 to Form 8-K)
Event 30 Jun 2026 · Published 30 Jul 2026
Limits: Quanta completed four acquisitions in the period, complicating organic comparison. Segment margins exclude corporate and amortisation; the consolidated margin includes them.
Research note
Shortlist H325 (MISLEADING as originally written). Narrating 7.3% as proof of 'volume, not pricing power' while omitting that it rose from 5.5% INVERTS what the quarter showed. Both numbers are narrated.
- FactFrontier · Aug 2026Primary sourceF48
Margin capture across the electrical value chain in the quarter ended 30 June 2026: Vertiv 22.6% adjusted operating margin (+410bps), GE Vernova Power 18.8% segment EBITDA margin (+240bps), GE Vernova Electrification 18.4% (+390bps), Eaton 23.1% total segment margin (-80bps), Hubbell Utility Solutions 21.2% adjusted (-130bps), Hubbell Electrical Solutions 16.7% operating (-480bps), Atkore 22.2% gross (-120bps), Modine Data Centers 20.2% gross (-960bps), EMCOR 10.6% operating, Quanta 7.3% consolidated operating (+180bps), GE Vernova Wind -13.6% segment EBITDA (-630bps).
Source: Company Q2 2026 earnings releases filed as exhibits to Form 8-K, SEC EDGAR
Event 30 Jun 2026 · Published Aug 2026
Limits: Margin definitions are NOT comparable across companies: gross, segment operating, adjusted operating and segment EBITDA margins are mixed. Every bar must be labelled with its own metric. The comparable signal is DIRECTION, not level. Several changes are affected by acquisitions.
Research note
Chartable series. The label discipline is the teaching, not a footnote.
- FactFrontier · Sep 2026JournalismF49
Year to date through 2 September 2026: Bloom Energy +138.1%, Powell +61.9%, Vertiv +58.5%, Quanta +43.4%, GE Vernova +37.8%.
Source: Yahoo Finance v8 chart API, dividend and split-adjusted daily closes, independently recomputed 2 September 2026
Event 2 Sep 2026 · Published 2 Sep 2026
Limits: Vendor data. Caterpillar was in the original basket and is DROPPED: it is a diversified machinery company whose backup-power business is a minority of revenue, so its move cannot carry the label.
Research note
Shortlist H441. Must be reported alongside F50 or it misleads.
- FactFrontier · Sep 2026JournalismF50
The same complex sits far below its own post-2023 highs on the same day: NuScale about -84%, Oklo about -80%, Powell about -48%, Vertiv about -32%, GE Vernova about -23%.
Source: Yahoo Finance v8 chart API, daily OHLC, independently recomputed 2 September 2026
Event 2 Sep 2026 · Published 2 Sep 2026
Limits: Each measured from that name's OWN peak, and those peaks fall on dates ranging from September 2025 to August 2026 — so this is not a common-window comparison.
Research note
Shortlist H030. 'Up strongly this year' and 'in a deep drawdown' are both true of the same names on the same day. Report both or mislead.
- FactPrimary sourceF51
Copper is only about 10% of the price of a power transformer. A 66% rise in the copper price raises the transformer price by about 7% — which the IEA judges 'unlikely to fundamentally undermine the economic viability of transmission and distribution projects.'
Source: IEA, Global Critical Minerals Outlook 2026, Chapter 3, chart p.245 and text p.248
Event May 2026 · Published 15 Jul 2026
Limits: Specific to 66-154 kV power transformers. Cost shares differ by voltage class and by conductor choice.
Research note
Shortlist H054. The standing course-level refusal is narrated as arithmetic, not as an assertion.
- FactFrontier · Aug 2026Primary sourceF52
And the direction is wrong for the story anyway: copper mine production FELL 1.1% in the first half of 2026, to 11,341 kilotonnes from 11,468, with capacity utilisation dropping to 77.1% from 81.0%.
Source: International Copper Study Group, Table 1 — World Refined Copper Production and Usage Trends
Event 30 Jun 2026 · Published 20 Aug 2026
Limits: Six months of data; monthly mine figures are volatile and heavily revised. World mine CAPACITY rose 3.8% over the same period.
Research note
Shortlist H055. Supply falling while the market runs a surplus is only possible if demand is not doing what the headlines say.
- FactPrimary sourceF53
Aluminium is not the escape hatch either. Its conductivity is about 60% of copper's, and although a 3-to-1 price ratio was long treated as the substitution threshold, the ratio has exceeded 3.5 to 1 for much of the past five years without triggering a major tipping point.
Source: IEA, Global Critical Minerals Outlook 2026, Chapter 2 pp.136-137
Event Apr 2026 · Published 16 Jul 2026
Limits: Substitution IS occurring in specific applications the IEA names — overhead lines, heat exchangers, some EV cabling. The claim is that no BROAD tipping point occurred.
Research note
Shortlist H019. The market ran the experiment for five years and the answer was no.
5 further audited series are recorded but not drawn
US total electricity end use, 2000-2025
Source: EIA Monthly Energy Review Table 7.6, series ELTCPUS
PJM Base Residual Auction clearing price by delivery year, Rest of RTO
Source: PJM Base Residual Auction Reports, Table 2
US data-centre siting actions by type, March 2025 - August 2026
Source: dcmap.us US Data Center Policy Tracker
Q2 2026 margin capture across the electrical value chain
Source: Company Q2 2026 earnings releases, SEC EDGAR
The post-interconnection-agreement cohort by fuel
Source: LBNL Queued Up: 2026 Edition
The strongest case against this
The seller refuses the crown, and the buyer is not talking about electrons
Carried at full strength, before the conclusion — not as a footnote.
The two strongest challenges to this episode both came from inside the evidence. GE Vernova's chief executive says his turbines are not the gating item; the IEA says high-end memory became a binding constraint on AI server production at a level broadly in line with power. Neither refutes the film. Strazik's own lead time is three years, so turbines are co-binding rather than abundant, and the IEA lists bottlenecks in the plural. Read completely, both say the same thing the episode says: 'electricity' is six constraints wearing one word, and the binding item is the powered building — shell, interconnection, permit and crew.
- F14
- F15
- F16
- F24
- F25
- F11
What remains uncertain
What we still do not know
Stated by the research team, in full, rather than smoothed over.
- No filed disclosure attributes a specific delayed AI deployment to power. Testimony exists (Nadella) and filed corroboration of the CATEGORY exists (NVIDIA's land/power/shell guarantees), but the specific disclosure does not. This is narrated on screen as the reason the reach line lands at three and a half.
- NVIDIA's 'certain supply constraints' names no stage, no quantity and no ranking against power. The film says so rather than inferring a chip bottleneck.
- Behind-the-meter generation is excluded from the public datasets by construction. That is a real limitation of this evidence base and is stated rather than researched around.
- This is a US evidence base about US grids. The film states the bound rather than implying global coverage.
- The dcmap.us tracker is a private aggregator that self-declares under-reporting of small local actions, so 56 actions is a floor, not a census.
What we refused to publish
13 claims we would not say — and why
The do-not-narrate list. Some are popular; some are true but unproven; some are simply not this note’s to make. Each refusal is enforced in production, not just recorded.
- RefutedX01
“Power and permitting are the proven binding constraint on AI compute.”
Verdict: REFUTED IN PART — the bar is on the word PROVEN, not on the evidence
Why: Written before the Nadella items were verified as SUPPORTED. There is now a named buyer on the record saying he has chips he cannot plug in, and a primary filing guaranteeing partners' land, power and shell obligations. What does NOT exist is a filed disclosure attributing a specific delayed AI deployment to power. The film says what each document does and does not establish, and draws the reach line at three and a half.
- RefutedX02
“Power is the binding constraint on AI compute, and the grid is what will stop the build-out.”
Verdict: REFUTED
Why: The IEA's own bottleneck section lists bottlenecks in the plural and finds high-end memory binding on the rate of AI server production, at a level broadly in line with power. The seller of the allegedly binding equipment says on the record that his turbines are not the gating item. 'Electricity' is six constraints, not one.
- RefutedX03
“Tucson blocked Amazon's Project Blue. / The project then moved to Marana.”
Verdict: REFUTED
Why: Two errors. The Council voted to end ANNEXATION negotiations for land that was never inside the city, so it could not block anything; and 'it moved to Marana' conflates Project Blue with a separate, larger ~600-acre Beale project. Project Blue proceeded on its original unincorporated Pima County site. Amazon's involvement was reported, never confirmed.
- RefutedX04
“New York banned data centers.”
Verdict: REFUTED
Why: EO 62 holds DISCRETIONARY STATE DEC permits for facilities of 50 MW or more. It does not touch local zoning, by-right development or federal permits, and it exempts applications already deemed complete. It also has no expiry date, which cuts the other way and is narrated too.
- RefutedX05
“Texas banned or halted data center construction. / Texas has 474 GW of data centre demand coming.”
Verdict: REFUTED
Why: Abbott's 3 August 2026 directive pauses an interconnection STUDY PROCESS pending an audit; it is not a construction ban. And the 474 GW is a request queue containing duplicate applications from developers shopping multiple sites — it is not demand, and the film does not narrate it as a quantity.
- Partly unverifiableX06
“AI data centers are why your electricity bill went up. / PJM capacity prices rose 833% because of data centers.”
Verdict: PARTIALLY UNVERIFIABLE
Why: New Jersey's regulator attributes a 17-20% residential increase to the CAPACITY AUCTION, which is a different and checkable claim. The auction step also spanned a change in accreditation rules, the last three prints cleared at an administrative cap, and by June 2026 New Jersey residential prices were up only 0.3% year on year. A Columbia review finds load growth can also REDUCE average bills. The film narrates the chain and its limits, never the headline.
Show the remaining 7 refused claims
- RefutedX07
“Power transformer lead times are 128 weeks as of 2026. / Transformer lead times are X years.”
Verdict: REFUTED
Why: 128.0 weeks is a Q2 2025 Wood Mackenzie reading, and it had DECLINED 10.4 weeks quarter over quarter. Multiple 2026 articles quote it as current; that is a dating error. The film gives the date and the direction, never the level as current.
- RefutedX08
“AI means buy copper miners. / Data centres are a major driver of global copper demand.”
Verdict: REFUTED
Why: Standing course-level refusal. Copper is about 10% of a transformer's price and a 66% copper move produces a ~7% transformer move. Copper mine production FELL 1.1% in H1 2026 while the market ran a surplus. Narrated out loud as the correction, never omitted.
- RefutedX09
“Gas turbine supply is the binding constraint on AI compute buildout. / Turbine makers are pure AI infrastructure plays.”
Verdict: REFUTED
Why: The chief executive of the largest Western turbine maker says twice on one call that his turbines are 'really not the gating item'. Data centres are around a fifth of that gas book. A sold-out order book is evidence of tightness, not of bindingness.
- RefutedX10
“Regulated utilities with large data-centre load are AI winners. / Every company exposed to electricity is an AI beneficiary.”
Verdict: REFUTED
Why: A regulated utility earns on capital invested times an allowed return, with a lag. Volume mostly passes through. AEP's authorised returns sit in a 9.7-9.8% band. The most obvious beneficiary may capture the least, and the film teaches the mechanism rather than asserting the conclusion.
- UnresolvableX11
“A bubble thesis, an overbuild verdict, or a capital-cycle judgement on the AI power build-out.”
Verdict: UNRESOLVABLE — MUST BE STATED AS UNKNOWN
Why: AI12's ground. The episode may observe that physical build-outs have historically overshot; it may not say this one will, and it does not.
- RefutedX12
“Interconnection queues are the data-centre queue. / There are 2,061 GW of projects queued because of AI data centre demand.”
Verdict: REFUTED
Why: LBNL's queue covers GENERATOR interconnection to the transmission grid only — not load, not distribution-connected, not behind-the-meter. Conflating generators wanting to connect with data centres wanting power is the most common error in AI-power commentary, and the film disarms its own biggest number on screen.
- RefutedX13
“Investment advice, a recommendation, or a valuation verdict on any named company.”
Verdict: REFUTED
Why: Course-level refusal. Companies are named only where a filed number, a lead time or a management statement does the work.
Evidence & sources
47 sources, by tier
Tier 1 is primary and authoritative — filings, regulators, official statistics. Journalism and books are attributed ingredients, never proof by reputation.
- JournalismAZ Luminaria and Tucson Spotlight / KVOA contemporaneous reporting of the 6 August 2025 Mayor and Council votesupports F01
- JournalismAZ Luminaria, 'Two Southern Arizona data centers move forward — so do fights over power, water and growth'supports F02
- JournalismAZ Luminaria construction reporting, corroborated by Pima County board recordssupports F03
- JournalismArizona Corporation Commission decision, reported by KJZZ and corroborated by KVOAsupports F04
- JournalismKJZZ 'The Show', corroborated by KVOA and Tucson Spotlightsupports F05
- Primary sourceUS EIA, Monthly Energy Review, Table 7.6, series ELTCPUS (Electricity End Use, Total) (opens eia.gov)supports F06
- Primary sourceUS EIA, Monthly Energy Review, Table 7.6 notes (opens eia.gov)supports F07
- Primary sourceLawrence Berkeley National Laboratory, Queued Up: 2026 Edition, slides 4, 7, 13, 18 (opens emp.lbl.gov)supports F08
- Primary sourceLawrence Berkeley National Laboratory, Queued Up: 2026 Edition (opens emp.lbl.gov)supports F09, F28
- Primary sourceLawrence Berkeley National Laboratory, Queued Up: 2026 Edition, slides 13, 16 (opens emp.lbl.gov)supports F10
- Primary sourceIEA, Key Questions on Energy and AI (World Energy Outlook Special Report), Section 1.3 'Physical bottlenecks' (opens iea.blob.core.windows.net)supports F11
- ResearchWood Mackenzie & American Clean Power, 'Making the connection: meeting the electric T&D supply chain challenge', Executive Summary (opens powermag.com)supports F12
- Primary sourceUS Department of Energy, Large Power Transformers and the US Electric Grid (2014)supports F13
- Primary sourceGE Vernova Q1 2026 earnings call, company-published webcast transcript (opens gevernova.com)supports F14, F15, F16, F18
- Primary sourceGE Vernova Q2 2026 earnings call and Q1 2026 call transcripts (opens gevernova.com)supports F17
- ResearchBG2Pod with Brad Gerstner and Bill Gurley, 'All things AI' — primary audio, transcribed at approximately 20:00-21:00supports F19
- ResearchBG2Pod, as above; analysis of the quoted wordssupports F20
- Primary sourceNVIDIA Corporation Form 10-Q, fiscal Q2 2027, Note 10 Commitments and Guarantees (accession 0001045810-26-000075) (opens sec.gov)supports F21
- Primary sourceNVIDIA Corporation Form 10-Q, fiscal Q2 2027, derivatives note (opens sec.gov)supports F22
- Primary sourceNVIDIA Corporation Form 10-Q, fiscal Q2 2027 (accession 0001045810-26-000075) (opens sec.gov)supports F23
- Primary sourceIEA, Key Questions on Energy and AI, Section 1.3 'Physical bottlenecks' (opens iea.blob.core.windows.net)supports F24, F25
- Primary sourceSynthesis of the AI06 evidence base; the standing AI05 finding, narrowedsupports F26
- Primary sourceLawrence Berkeley National Laboratory, Queued Up: 2026 Edition, slides 25, 28, 29 and conclusions (opens emp.lbl.gov)supports F27
- Primary sourceOncor Electric Delivery Company LLC / Sempra, Exhibit 99.2 to Form 8-K (opens sec.gov)supports F29
- Journalismdcmap.us, US Data Center Policy Tracker (opens dcmap.us)supports F30
- Journalismdcmap.us tracker methodology, assessed (opens dcmap.us)supports F31
- Primary sourcePJM Interconnection Base Residual Auction Reports, Table 2, and PJM news releases (opens pjm.com)supports F32
- Primary sourcePJM 2027/2028 Base Residual Auction Report and subsequent auction releasesupports F33
- Primary sourceNew Jersey Board of Public Utilities, 'NJBPU Announces Conclusion of New Jersey's Annual Electricity Supply Auction' (opens nj.gov)supports F34
- Primary sourceUS EIA electricity data, New Jersey residential price, assessed against the 2025 stepsupports F35
- ResearchCenter on Global Energy Policy, Columbia SIPA — 'The Effects of Load Growth on Electricity Prices in the United States: A Literature Review' (opens energypolicy.columbia.edu)supports F36
- Primary sourceAmerican Electric Power Q2 2026 Form 10-Q, MD&A — large load tariff proposalssupports F37
- Primary sourceOffice of Governor Kathy Hochul, Executive Order No. 62 (official text) (opens governor.ny.gov)supports F38, F39
- ResearchLetter from Governor Greg Abbott to the PUCT and ERCOT, 3 August 2026; ERCOT Market Notice M-A080326-01supports F40
- Primary sourceUS EIA, August 2026 Short-Term Energy Outlook (opens eia.gov)supports F41
- Primary sourceAmerican Electric Power Form 10-Q, Rate Matterssupports F42
- Primary sourceCoreWeave, Inc. Form 10-Q for the quarter ended June 30, 2026, Part II Item 1A Risk Factorssupports F43
- Primary sourceCoreWeave, Inc. Form 10-Q, Part II Item 1A Risk Factorssupports F44
- Primary sourceComfort Systems USA Form 10-Q for the quarter ended June 30, 2026 (Revenue by Type of Customer)supports F45
- Primary sourceEMCOR Group Q2 2026 earnings release (accession 0000105634-26-000112)supports F46
- Primary sourceQuanta Services Q2 2026 earnings release (Exhibit 99.1 to Form 8-K)supports F47
- Primary sourceCompany Q2 2026 earnings releases filed as exhibits to Form 8-K, SEC EDGARsupports F48
- JournalismYahoo Finance v8 chart API, dividend and split-adjusted daily closes, independently recomputed 2 September 2026supports F49
- JournalismYahoo Finance v8 chart API, daily OHLC, independently recomputed 2 September 2026supports F50
- Primary sourceIEA, Global Critical Minerals Outlook 2026, Chapter 3, chart p.245 and text p.248supports F51
- Primary sourceInternational Copper Study Group, Table 1 — World Refined Copper Production and Usage Trendssupports F52
- Primary sourceIEA, Global Critical Minerals Outlook 2026, Chapter 2 pp.136-137supports F53
Complete evidence depth
The research desk
Everything the research evaluated before it was distilled — including what it rejected, and why.
This note predates DowJo’s research-preservation standard, so the pre-collapse shortlist was not kept. Everything the film was allowed to say — and refused to say — is above.
Community
Talk it through
Discuss this research
Members only · in 📡 Intelligence Watch
Challenge the argument, bring evidence, or ask what would change our mind. This note is discussed in 📡 Intelligence Watch, a DowJo room where members compare reads. Filings, news events, and what they actually mean — the discussion room for the intelligence feed.
Read and reply, then keep following the story — you come straight back to this note.
Education-first ground rules apply in every room: mechanisms and evidence, never calls.
Now train it
Take it further
Reading is where judgment starts. Practice is where DowJo measures it — and remembers what to train next.
Train it
Can you spot what the market already priced in?
Five reps on today's tape. Commit a call before the market grades it.
Train itTrain it
Need the concept first?
Learn it visually in the Academy, then come back to the evidence.
Learn itLearn the concepts underneath
Join the discussion
Challenge the argument, bring evidence, or ask what would change our mind — in the open, with other members.
MentorAsk Jo what could invalidate this thesis.
Jo reads this note before answering. Sign in to ask, with this evidence attached — you come straight back here.
Ask Jo with this evidence attachedProvenance — where this note comes from
This page is a deterministic projection of canonical research artifacts. It adds presentation and discovery; it never adds, removes or softens a finding. Question taken from the artifacts; thesis from the script. Projected 21 Sep 2026 by dowjo-research-projector v1.1.0 from origin commit c83c8797ab79.
| Artifact | Path (origin-relative) | Identity | Version |
|---|---|---|---|
| Episode registry | course/episodes.json | sha256 829382d56a92… | — |
| Evidence packet | course/research/AI06-evidence-packet.json | sha256 ab109d9d0946… | compiled 2026-09-02 · rev 1 |
| Approved script | course/scripts/AI06-six-constraints-one-word.json | sha256 e1e2fd4d29cf… | v 1 |
| Episode manifest | course/manifest/AI06.manifest.json | sha256 d84dd960deef… | — |
| Approval record | renders/approved/AI06-FINAL.json | sha256 960b4bc50b76… | compiled 2026-09-20 |
| Poster still | qa/stills-AI06/RESEARCH-POSTER.png | sha256 86f52a7c2717… | — |
Approved master (AI06-final02-corrected.mp4): sha256 61027bbdedd0a7f8b5f4ad50a5dd418fd79ac65ff989a5789e83c612998739ed
Commercial disclosure: none. No affiliate relationship, review copy, sponsorship or publisher relationship applies to this note.
For education only. Not financial advice. No buy, sell or hold recommendations, ever.
Related research
That looks interesting too
Investing in the AI Era · Episode 1
Everyone Knows AI Is the Future. So What Do You Actually Invest In?
You can be completely right about AI and completely wrong about the investment.
Shares Artificial Intelligence, AI Infrastructure, Markets
Investing in the AI Era · Episode 5
The Boring Component That Became the Bottleneck
A bottleneck is not a property of a component.
Shares AI Infrastructure, Artificial Intelligence, Markets
Investing in the AI Era · Episode 10
Why Did Six Different Stocks Move at the Same Time?
They were never six different stocks.
Shares Markets, Artificial Intelligence, AI Infrastructure, Investing